


Intended Level of Study
5 years of post-secondary education
ECTS
120 credits
Duration
2 years
Training Structure
School of Economics
Language(s) of Instruction
French
Overview
The Master’s program in Money, Banking, Finance, and Insurance (MBFA) atthe Faculty of Economics in Montpellier trains specialists capable of analyzing, evaluating, and modeling various financial risks. This program develops advanced skills in the valuation of financial products, risk management, and banking regulation, as well as an understanding of how financial institutions and financial markets operate.
The master's program also prepares students to conduct economic and financial studies for public agencies, banks, insurance companies, or firms in the financial sector.
The Benefits of the Training Program
-
HIGHLY VOCATIONAL TRAINING
-
MASTERY OF TOOLS AND METHODS
- PATHWAYS OPEN TO APPRENTICESHIPS
Objectives
The MBFA Master’s program aims to train highly qualified experts in the fields of banking, finance, insurance, financial markets, and financial engineering who are capable of:
-
Analyze, assess, and model the financial risks faced by financial institutions (banks, insurance companies, etc.);
-
Acquire a thorough understanding of finance and advanced technical skills (econometrics, quantitative finance, risk management, programming, financial databases);
-
Be able to hit the ground running in roles in finance, risk management, consulting, or financial product management.
Expertise and Skills
Expertise
-
Analyze, assess, and model financial risks (market, credit, liquidity, and actuarial).
-
Evaluate complex financial products and build structured portfolios.
-
Apply methods from modeling, econometrics, and financial engineering.
-
Use specialized financial market software and IT tools.
-
Conduct analysis and research in finance and economics.
Skills
-
Proficiency in financial and actuarial risk management.
-
Expertise in banking, finance, and regulation.
-
Ability to analyze and assist with financial decision-making.
-
Autonomy in processing complex financial data.
International Dimension
Starting in their second year, students can study at one of the 60 universities with which the School of Economics has partnerships through the ERASMUS+, inter-university exchange agreements, and CHARM-EU exchange programs.
Organization
Knowledge Assessment
Master’s programs at the School of Economics are structured over two years and four semesters and are based on an assessment system designed to measure students’ learning progress in a gradual and comprehensive manner. At the end of each semester, the skills, competencies, and knowledge acquired in each course unit (UE) are assessed in one of two ways: through continuous assessment or a final exam.
Continuous assessment allows for regular monitoring of student progress through various forms of evaluation: proctored exams, graded tutorials, presentations, projects, document analyses, and active participation in class. This approach encourages regular attendance, consistent work, and the gradual acquisition of skills.
The final exam, on the other hand, consists of a written or oral test administered at the end of the semester. Its purpose is to assess the student’s overall mastery of the concepts taught and their ability to apply their knowledge in a structured and in-depth manner.
Special Features
Students with disabilities, young entrepreneurs, and elite athletes can receive personalized support.
This may take the form of academic accommodations, pedagogical adjustments, or specific rights, in order to enable students to best balance their personal or professional commitments with their university studies. Depending on the situation, these measures may include an adapted class schedule, modified assessment procedures, attendance accommodations, individualized support, or dedicated support services.
Open on an alternating basis
The apprenticeship program is based on the principle of alternating between academic and practical instruction provided at the university and the acquisition of practical skills at a workplace. The frequency of this alternation varies depending on the program but follows a schedule established in advance.
The apprenticeship contract is a special type of employment contract that allows the student to hold dual status: as a student and as a full-fledged employee of the company.
MANDATORY INTERNSHIP IN M1 AND M2
- Business and Corporate Account Manager
APPRENTICESHIPS AVAILABLE IN M2
- Financial Engineering
- Economic and Financial Information System
economie.edu.umontpellier.fr/carriere/formation-en-apprentissage/
Internships, supervised projects
Internship | Possible |
|---|---|
Duration of the internship | A maximum of 924 hours, or 6 months |
Internship Abroad | Possible |
A true immersion in the professional world, it allows students to apply the knowledge they’ve acquired in class, discover how organizations operate, and compare theory with practice. To get the most out of it, thorough preparation is essential: learn about the host organization, define your goals, draw on what you’ve learned, and prepare for professional demands.
All Master's programs offer the opportunity to complete an internship.
In the first year of the master's program, an internship is possible but optional. It must be related to the program.
The internship may begin at the end of the second-semester exams or take place during university breaks. In any case, it must end no later than August 31, regardless of whether the student is enrolled in a Bachelor’s program, a first-year Master’s program, or a University Diploma program.
In the second year of the Master's program, the internship is required.
The start date is set in consultation with the academic advisor, generally between February and March, to align with the academic calendar and the requirements for the final thesis. Regardless of the period chosen, the internship mustend no later than September 30.
economie.edu.umontpellier.fr/carriere/partir-en-stage/
Program
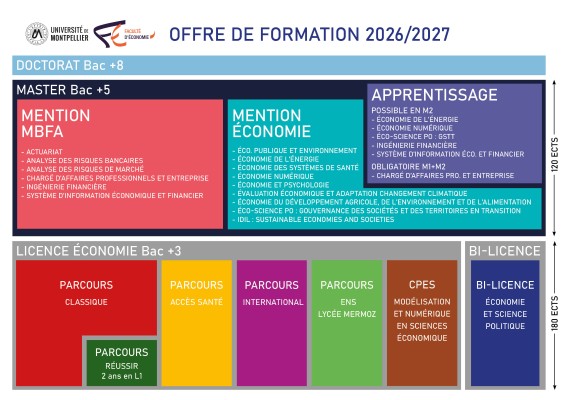
Select a program
Actuarial Science
The Actuarial track is one of the tracks within the Currency, Banking, Finance, and Insurance (MBFA) program in the School of Economics.
It aims to provide students with a solid foundation of theoretical and methodological knowledge that will enable them to pursue a career as an actuary, while also preparing future researchers in the fields of actuarial science, finance, and insurance.
What is an actuary?
An actuary is a professional who specializes in applying probability and statistics to issues related to insurance, finance, and social security.
An actuary’s role involves analyzing and quantifying risks, assessing their financial impact, and estimating the associated future cash flows. To do this, actuaries use advanced mathematical tools—primarily drawn from probability theory and statistics—to model and predict future events such as:
-
the length of human life,
-
the frequency of claims,
-
or the extent of the associated financial losses.
Theoretical Econometrics
5 creditsMarket Finance
4 creditsMonetary and Financial Macroeconomics
3 creditsForecasting Methods
5 creditsAlgorithms and Programming
3 creditsData Mining and Big Data
Data Warehouse
Language Selection List
Choose one of the following two options:
Financial English 1
2 creditsSpanish 1
The Economics of Bancassurance
3 credits
Introduction to Stochastic Calculus
4 creditsCorporate Finance
4 creditsIntroduction to SAS / Excel VBA
2 creditsActuarial Models in Excel VBA
3 creditsTime Series Econometrics
5 creditsTechnical Analysis
2 creditsApplied Econometrics Project
5 creditsActuarial Techniques
3 creditsChoose one of the following two options:
Financial English 2
2 creditsSpanish 2
2 credits
Optional
Financial Markets and Financial Theory
2 creditsProfessional Development Conferences
Trading Algorithm
1 creditPortfolio Management Using R
1 creditNon-Life Actuarial Science
3 creditsFinancial Analysis (Bank of France)
1 creditIntroduction to Artificial Intelligence in Python
0.5 creditsPrimary stock market: initial public offering
0.5 creditsStochastic Calculus
2 creditsFinancial English
1 creditEnterprise Risk Management
1 creditExploratory Statistics (SAS)
1 creditComputer Skills (VBA)
1 creditModeling Emerging Risks
2.5 creditsLife Insurance Actuarial Science
2.5 creditsCybersecurity and Cryptography
1 creditApplied Econometrics in Finance
2 creditsEconometrics of Financial Markets
2 creditsFinancial Big Data
1 creditFinTechs, Blockchain, and Cryptocurrencies
1 creditNumerical Methods in Actuarial Science "VBA"
2 creditsBanking and Insurance Regulations
1 credit
CHOICE 1
30 creditsChoose 1 or 2 out of 2
Research thesis as part of a research track
30 credits3- to 6-month internship
30 credits
Introductory Research Seminars
Banking Risk Analysis
The Banking Risk Analysis track of the MBFA Master’s program trains professionals and researchers specializing in banking and financial risk analysis as well as data science. It combines modern programming, statistical methods, and the analysis of large financial databases to address the sector’s emerging challenges.
The program takes into account developments in the banking and finance sectors, the complexity of international transactions, and new prudential regulatory requirements such as Basel III—particularly regarding liquidity risk and asset-liability management (ALM)—as well as proficiency in artificial intelligence tools. Classes in quantitative subjects are held in the Trading Room.
The program is highly career-oriented thanks to partnerships with banking institutions, presentations by industry professionals, conferences on big data and AI, and applied projects, all of which facilitate access to internships andemployment. The majority of graduates enter the workforce within six months, with an employment rate of over 80 percent.
Choose one of the following two options:
Financial English 1
2 creditsSpanish 1
Theoretical Econometrics
5 creditsMarket Finance
4 creditsMonetary and Financial Macroeconomics
3 creditsForecasting Methods
5 creditsAlgorithms and Programming
3 creditsData Mining and Big Data
Data Warehouse
The Economics of Bancassurance
3 credits
Optional
Choose one of the following two options:
Financial English 2
2 creditsSpanish 2
2 credits
Introduction to Stochastic Calculus
4 creditsCorporate Finance
4 creditsIntroduction to SAS / Excel VBA
2 creditsBanking Techniques
3 creditsTime Series Econometrics
5 creditsTechnical Analysis
2 creditsApplied Econometrics Project
5 creditsFinancial Mathematics Using Excel VBA
3 credits
Professional Development Conferences
Financial Markets and Financial Theory
2 creditsNumerical Methods in Banking "VBA"
2 creditsTrading Algorithm
1 creditPortfolio Management Using R
1 creditFinancial Analysis (Bank of France)
1 creditPrimary stock market: initial public offering
0.5 creditsStochastic Calculus
2 creditsOperational and Compliance Risks
2 creditsFinancial English
1 creditIntroduction to Artificial Intelligence in Python
0.5 creditsExploratory Statistics (SAS)
1 creditComputer Skills (VBA)
1 creditFinancial Big Data
1 creditCredit Risk
2 creditsCybersecurity and Cryptography
1 creditApplied Econometrics in Finance
2 creditsEconometrics of Financial Markets
2 creditsAsset-Liability Management (ALM)
2 creditsInterest Rate Risk
2 creditsFinTechs, Blockchain, and Cryptocurrencies
1 creditNumerical Methods in Actuarial Science "VBA"
2 creditsProgramming in R
Banking and Insurance Regulations
1 credit
Introductory Research Seminars
CHOICE 1
30 creditsChoose 1 or 2 out of 2
Research thesis as part of a research track
30 credits3- to 6-month internship
30 credits
Market Risk Analysis
The Market Risk Analysis program is designed to train both professionals and researchers specializing in the field of finance, with a particular focus on products traded on financial markets, such as stocks, bonds, derivatives, currencies, and commodities. The program combines a solid theoretical foundation with an in-depth quantitative approach, enabling students to understand how markets function and the mechanisms behind the valuation of financial instruments.
Students develop skills in managing and measuring financial risk through the use of advanced statistical methods, such as volatility analysis, Value at Risk (VaR), Expected Shortfall (ES), and backtesting of risk models. They also learn to assess portfolio exposure, identify major risk factors, and implement effective hedging strategies.
Choose one of the following two options:
Financial English 1
2 creditsSpanish 1
Theoretical Econometrics
5 creditsMarket Finance
4 creditsMonetary and Financial Macroeconomics
3 creditsForecasting Methods
5 creditsAlgorithms and Programming
3 creditsData Mining and Big Data
Data Warehouse
The Economics of Bancassurance
3 credits
Introduction to Stochastic Calculus
4 creditsAsset Valuation
3 creditsCorporate Finance
4 creditsIntroduction to SAS / Excel VBA
2 creditsPortfolio Allocation
3 creditsTime Series Econometrics
5 creditsTechnical Analysis
2 creditsApplied Econometrics Project
5 creditsOptional
Choose one of the following two options:
Financial English 2
2 creditsSpanish 2
2 credits
Numerical Methods
3 creditsFinancial Markets and Financial Theory
2 creditsVBA Programming
1 creditStochastic Calculus
2 creditsPortfolio Management
4 creditsFinancial English
1 creditTrading Algorithms
2 creditsData Mining and Big Data
3 creditsExploratory Statistics (SAS)
1 creditComputer Skills (VBA)
1 creditMarket Risks
4 creditsFinancial Econometrics
5 creditsProgramming in R and Python
1 credit
CHOICE 1
30 creditsChoose 1 or 2 out of 2
Research thesis as part of a research track
30 credits3- to 6-month internship
30 credits
Professional Speakers
Introductory Research Seminars
Manager of Professional and Corporate Affairs
TheMaster’s in Professional and Corporate Account Management (CAPE) trains professional and corporate account managers to fulfill their responsibilities of managing, advising, and developing a client portfolio consisting of artisans, merchants, independent professionals, microbusinesses, and small and medium-sized enterprises, while taking into account developments in the banking and financial sectors and regulatory requirements.
This program provides a solid foundation in economic, banking, and financial analysis, as well as proficiency in quantitative and digital analytical tools, preparing students for careers in professional and corporate business centers.
The training program enables participants to acquire essential technical, business, and interpersonal skills, while developing a solid understanding of risk management—which is essential for advancing in this industry.
Bank Forecast
8 creditsMonetary and Financial Macroeconomics
3 creditsImplement an appropriate, enhanced relationship-building approach
8 creditsBanking and Financial English
2 creditsBanking Modeling
9 credits
Credit
2 creditsCorporate Finance
4 creditsAccount Opening and Related Services
4 creditsFinancial Mathematics Using Excel VBA
3 creditsInsurance
2 creditsSupporting clients through life events
2 creditsExpand the client portfolio and manage risks in
4 creditsSupervised Project
5 creditsBank Statement
2 creditsProfessional Review and Evaluation of the Internship Period
2 credits
Financial Engineering
The Financial Engineering track of the MBFA Master’s program is designed to train bothprofessionals and specialized researchers. It prepares students to become experts inadvanced financial engineering techniques, capable of analyzing and solving complex problems within a strategic and global framework.
The program emphasizes the international dimension of financial markets and institutions, enabling graduates to understand global economic and financial issues. Students develop both technical and analytical skills, allowing them to devise innovative solutions, structure complex financial products, and address the strategic challenges faced by banks, asset management firms, insurance companies, and international financial institutions.
Choose one of the following two options:
Financial English 1
2 creditsSpanish 1
Theoretical Econometrics
5 creditsMarket Finance
4 creditsMonetary and Financial Macroeconomics
3 creditsForecasting Methods
5 creditsAlgorithms and Programming
3 creditsData Mining and Big Data
Data Warehouse
The Economics of Bancassurance
3 credits
Choose one of the following two options:
Financial English 2
2 creditsSpanish 2
2 credits
Introduction to Stochastic Calculus
4 creditsCorporate Finance
4 creditsIntroduction to SAS / Excel VBA
2 creditsProject Financing Using Excel VBA
3 creditsTime Series Econometrics
5 creditsCorporate Taxation
3 creditsTechnical Analysis
2 creditsApplied Econometrics Project
5 creditsOptional
Mergers, Spin-offs, LBOs, Bankruptcies, Restructuring
2 creditsQuantitative Risk Management
2 creditsFinancial Markets and Financial Theory
2 creditsInvestment Science
3 creditsPortfolio Management Using R
1 creditInnovative Financing Transactions
1 creditFinancial Analysis (Bank of France)
1 creditAdvanced Financial Management: "Case Studies"
2 creditsStochastic Calculus
2 creditsTax Optimization: "Case Studies"
2 creditsAudit and Control: "Case Studies"
1 creditFinancial English
1 creditExploratory Statistics (SAS)
1 creditComputer Skills (VBA)
1 creditInternational Accounting (GAAP or IFRS)
2 creditsProject Management and Implementation
1 creditPanel Econometrics
2 creditsFinTechs, Blockchain, and Cryptocurrencies
1 creditBanking and Insurance Regulations
1 creditStrategy and Corporate Governance
1 credit
CHOICE 1
30 creditsChoose 1 or 2 out of 2
Research thesis as part of a research track in
30 credits3- to 6-month internship
30 credits
Introductory Research Seminars
IGF M2 Theses
30 creditsChoose one of the following two options:
Internship (Apprentices)
30 credits
Economic and Financial Information System
The Economic and Financial Information Systems (SIEF) track is designed to provide students with a comprehensive education at the intersection of economics, finance, and information technology. The program begins with a study of economic and financial fundamentals, including macroeconomics and financial models (VAR, VECM), before focusing on quantitative subjects such as econometrics and stochastic calculus.
The IT component of the program is also central. Students learn about information systems, algorithms, and programming (Python, VBA, JavaScript), as well as database management and data warehousing. New technologies are explored through big data, data mining, data visualization, and artificial intelligence. Finally, the program includes the study of information system environments, covering IS modeling and design, network and data security, as well as the legal aspects related to personal data protection (GDPR).
Theoretical Econometrics
5 creditsMarket Finance
4 creditsMonetary and Financial Macroeconomics
3 creditsForecasting Methods
5 creditsAlgorithms and Programming
3 creditsData Mining and Big Data
Data Warehouse
The Economics of Bancassurance
3 creditsChoose one of the following two options:
Financial English 1
2 creditsSpanish 1
Introduction to Stochastic Calculus
4 creditsCorporate Finance
4 creditsIntroduction to SAS / Excel VBA
2 creditsVBA Programming
3 creditsEconometrics of Qualitative Variables
3 creditsTime Series Econometrics
5 creditsTechnical Analysis
2 creditsApplied Econometrics Project
5 creditsOptional
Choose one of the following two options:
Financial English 2
2 creditsSpanish 2
2 credits
Designing an Information System (IS)
3 creditsDatabase Management
2 creditsProgramming Techniques
2 creditsData Mining and Big Data
3 creditsPoll
2 creditsIT Law (Polytech)
2 creditsData Warehouse
3 creditsModeling an IS (Information System)
3 creditsExploratory Statistics (SAS)
1 creditComputer Skills (VBA)
1 creditData Visualization Design
2 creditsEconometrics
3 creditsSecurity
3 credits
Choosing Between an Internship and a Thesis
30 creditsChoose one of the following two options:
M2 SIF Internship
30 creditsResearch thesis as part of a research track
30 credits
Introductory Research Seminars
Optional
Admission
Admission Requirements
- For the Master 1 program: Applicants must hold or be in the process of earninga bachelor’s degree (or equivalent, bac+3) in economics or a related field, recognized in France or Europe.
- For the Master 2 program: Have successfully completed at least 4 years of higher education (Bac +4 / 240 ECTS) in fields related to economics or similar disciplines.
Registration Procedures
First year of the master's program
If you wish to apply for admission to the first year of a master's program, you must submit your application through the Mon Master platform .
Second year of the master's program
To gain admission to the second year of the master's program based on academic equivalence, the ecandidat application process is required.
economie.edu.umontpellier.fr/candidatures/candidatures-et-admissions/
Target Audience
Students from the Montpellier Academy, the Occitanie region, France, and abroad.
Tuition Fees
Tuition fees are set each year by the Ministry of Higher Education. They are accompanied by the Student and Campus Life Contribution (CVEC).
The entire program is free for students receiving scholarships.
Recommended Prerequisites
A strong background inmicroeconomics, macroeconomics, mathematics, statistics, and econometrics is essential. Depending on the intended career path, certain course options may be particularly valuable.
And then
Continuing Education
Master’s degree graduates can continue their studies, notably bypursuing a Ph.D. in economics, either in France or abroad, particularly those interested in research or higher education. Additional specialized programs (university degrees) may also be considered depending on one’s career goals.
Employment Placement
The MBFA degree prepares students for careers in the banking, finance, insurance, and financial markets sectors.
In particular, it prepares students for careers in:
-
Financial Risk Analyst (Market, Credit, Liquidity),
-
Analytical Actuary,
-
Market operator,
-
Portfolio Manager,
-
Financial Analyst,
-
Back-office and risk management functions,
-
Economic and financial analyst at public or private organizations.
It also allows students to pursue doctoral studies or become involved in applied research.
https://osipe.edu.umontpellier.fr/masters/